The three Seed numbers that decide your round
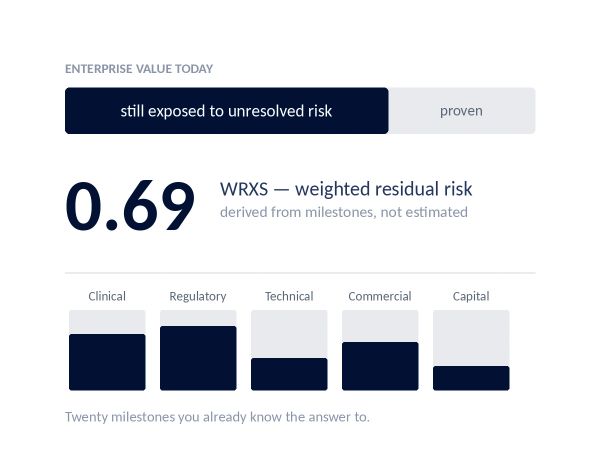
Residual risk - WRXS
The share of your enterprise value still exposed to unresolved risk. You cannot name it. You can name which milestones you have hit across clinical, regulatory, technical, commercial and capital — and that is what we ask. The score falls out of twenty yes-or-no answers you already know.
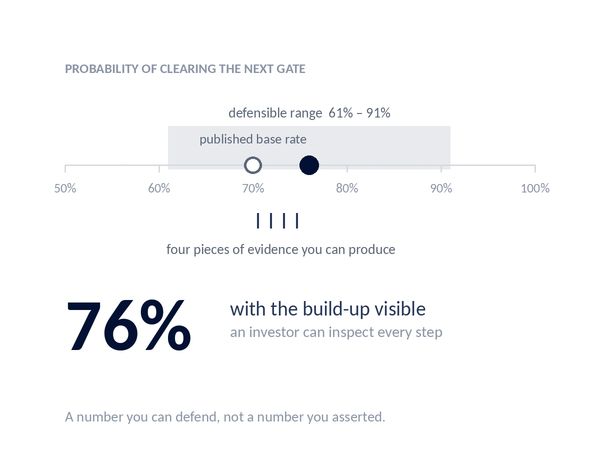
Probability of clearing the next gate
We start from a published base rate for your milestone and pathway, then move it on four pieces of evidence you can produce: predicate strength, pre-sub feedback, your strongest data tier, and pathway status. The result is a range with a build-up an investor can inspect.
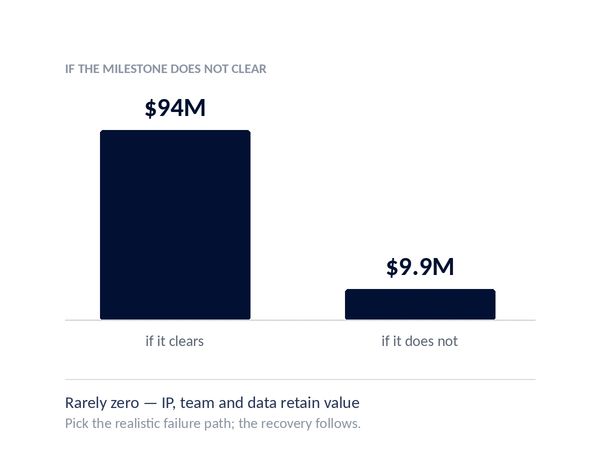
What the company is worth if it fails
Rarely zero. IP, team and data retain value. Pick the realistic failure path and the recovery figure follows from today’s valuation — with the reasoning visible.
The three Series A numbers that decide your round

Forward value — the pre-money
The number the whole round hangs on, and the one you cannot anchor with comps. We build it forward — your market, the share you can realistically hold, and what a strategic acquirer pays — then discount it for time and weight it by the odds of clearing the gates ahead. What comes back is a defensible range and the few assumptions that move it, not a single figure an investor can pick apart.

Ownership
You can run your own cap table; what is harder to see is what a specific pre-money and option-pool top-up do to your slice once pro-rata and any secondary are layered in. We price the round on your existing stack and show ownership and dilution, founder by founder, before and after. Whether you are setting the terms or weighing a lead's, you know exactly what you are giving up.

Terms at Exit
The pre-money is only half the deal — the preference terms decide who actually gets paid, and how much, at exit. We run the full stack of liquidation preference, participation, and seniority through the exit waterfall, showing what each term costs you across a range of outcomes. You walk into the negotiation knowing which points are worth conceding and which are worth a fight.
The number, and the defense of the number.
Anyone can hand you a valuation. Almost nobody will show you the arithmetic underneath it, tell you which inputs it is hostage to, and state plainly what it cannot prove.
What you get from Core Delta is not an opinion with a decimal point. It is a price your evidence supports, the build-up behind it, what each level costs you in dilution, and the objections you should expect — with the answer to each.

What we do NOT do
We take no fee contingent on a transaction. We are paid for the analysis whether you raise or not — it is the only arrangement in which the number stays honest.
We do not provide legal, regulatory, tax or investment-banking services, and we do not issue valuation opinions.
We do not claim the model predicts outcomes. It has not been back-tested, and we say so on the front page of every deliverable.
If you are in or planning a raise, start with the hour.
If you are not in a financing conversation yet, and not planning one soon, this will not help you — come back when you are, and it will.